The reverse mortgage clock on a Plainview house
Families reach us on a reverse mortgage having lost a month simply working out what the loan is. Somebody finds a statement, nobody recognizes the lender, and by the time the picture is clear the deadline is closer than it should be.
That window is real, but it is not a trapdoor. Servicers have discretion, extensions do get granted, and a signed contract is the strongest thing you can put behind a request for one. We have worked reverse mortgage payoffs across Nassau County and the pattern is consistent.
What the heirs actually owe on a reverse mortgage
The balance on a reverse mortgage grows rather than shrinks, because interest is added instead of paid. After a long borrowing period the number can look alarming next to what the house would sell for.
Do not panic at that figure on its own. What heirs are actually liable for depends on the reverse mortgage documents and on whether the loan is federally insured, and it is frequently less than the raw balance suggests. That is a question for an attorney, and it is worth asking before anyone decides anything.
The Plainview market underneath this
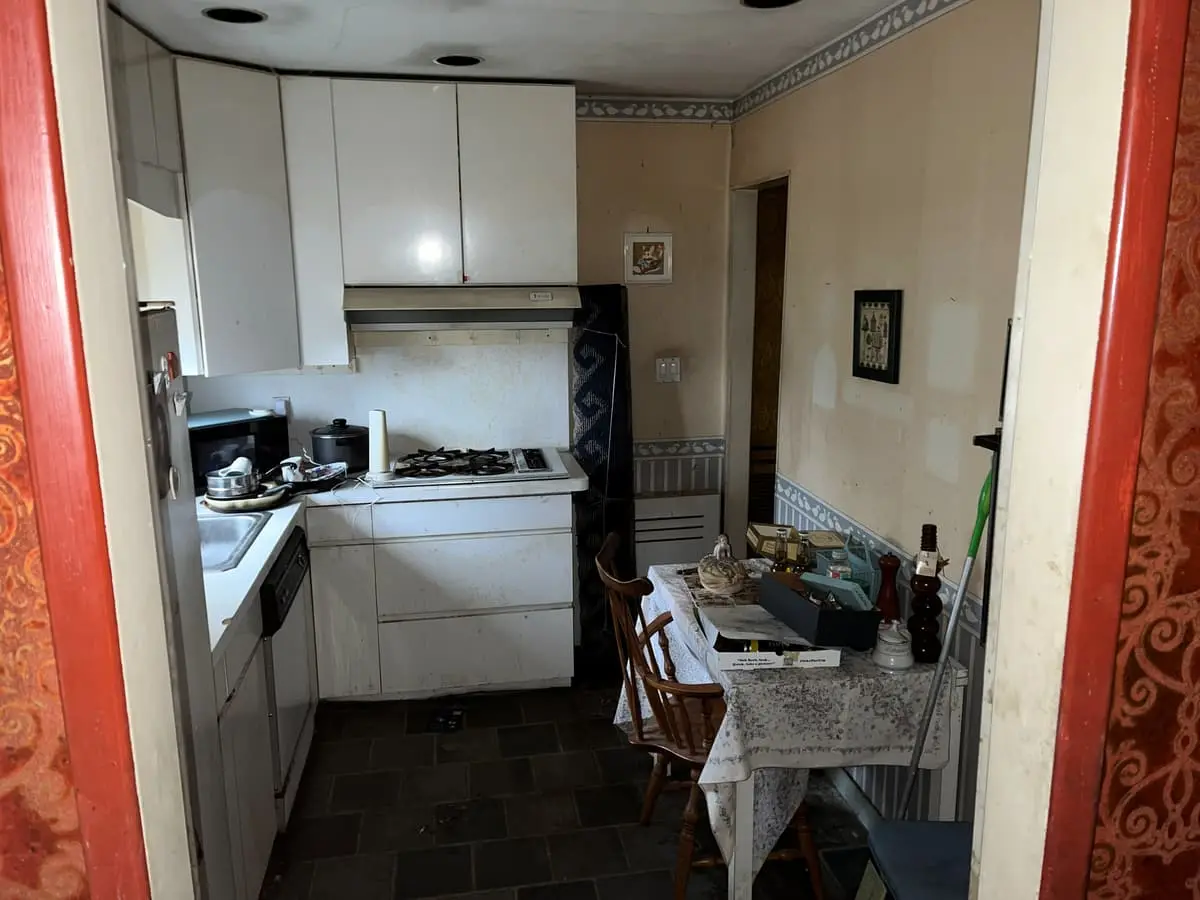
The median is up 10.23% year over year as of 2026-05. A firming market gives you a little room for error on price, which is worth more than it sounds when the house is not in showable condition. At a $970,000 median, Plainview buyers are paying enough that they expect the house to be finished. A dated kitchen is a deduction in a cheaper market and close to disqualifying in this one, which is why unrenovated houses here sit while the renovated ones move. The median house here goes under contract in about 28 days, which is quick for Long Island. It is also a figure that only applies to property in showable condition.
A three-bedroom on Gerhard Road. A three-bedroom on Knickerbocker Road North. A two-bedroom on Manetto Hill Road. All of them in Plainview, all bought by us.
What we bring, beyond the money
Reverse mortgage estates are where an inexperienced buyer does real damage. A financed buyer who collapses at week six of a deadline like this can cost a family the house outright.
We buy with our own funds, we have worked these payoffs in Nassau County, and we know how the servicers behave. We will support an extension request with a signed contract, coordinate with your attorney, and tell you plainly if the numbers mean the heirs are better off handing the keys back instead.
Why a reverse mortgage deadline rewards certainty
Retail buyers are not built for a reverse mortgage timetable. Their rate lock expires, their appraisal ages, their underwriter asks for one more document, and none of it bends for a servicer's letter.
We close with our own funds, which removes every one of those clocks. On a payoff with a fixed deadline that is not a small convenience. It is the difference between meeting the deadline with a clean payoff and watching the servicer begin foreclosure because the sale ran a month long.
What the two paths cost in Plainview
These are the two routes open to you with a house with a reverse mortgage, priced against what Plainview houses actually sell for.
Work it against Plainview's own numbers. The median sale here is $970,000. A 5% commission on that is $48,500, and seller closing costs of about 2% add roughly $19,400. Those are costs we can cover on our side. That is $67,900 gone before anyone counts the repairs it took to get the house listable.
There are two waits in a listed sale and people usually only count the first. In Plainview the median house takes about 28 days to go from listed to a signed contract. Then it waits again, typically 45 to 60 days, while the buyer's lender orders an appraisal and underwrites the loan. Call it 73 to 88 days from sign to keys, assuming nothing goes wrong.
The part worth understanding is what a signed contract actually guarantees, which is less than most sellers assume. A retail buyer with a mortgage contingency can walk away right up to the end. If they do not qualify, if the appraisal comes in under the price, if they change their mind and let the financing lapse. A share of deals die exactly there, after months of waiting, and the house goes back on the market with time on it. We are not borrowing anything, so there is no lender to satisfy, no appraisal to come in low and no contingency to exercise.
| Listing with an agent | Selling to us | |
|---|---|---|
| Sale price | $970,000 (Plainview median) | Our written offer |
| Commission | −$48,500 | None |
| Seller closing costs | −$19,400 | We can cover them |
| Repairs before listing | Out of pocket | None |
| Cleanout | Yours | Ours |
| Showings | Until it sells | One visit |
| Listed to signed contract | 28 days (Plainview median, once listable) | 24 hours to a written offer |
| Contract to closing | 45 to 60 days (waiting on the buyer's lender) | A date you choose |
| Total wait | 73 to 88 days if nothing falls through | Yours to set |
| Can the buyer walk? | Yes (mortgage contingency runs to the end) | No financing to fall through |
| Before repairs and carrying | $902,100 | The number we put in writing |
The listing column assumes a 5% commission and seller closing costs of about 2%. Both vary. We have not subtracted repairs or the cost of carrying the house while it sits, because those depend on the property. A house in good condition listed with a good agent can absolutely beat a cash offer, and we will say so if that is your situation.
If your parent has moved into care in Plainview
The rule that catches people is the one about occupancy. A reverse mortgage generally requires the borrower to live in the home, so a permanent move into care can trigger the payoff just as surely as a death does.
Unlike a death, nobody sends the family a letter about it right away. If your parent has moved out and their reverse mortgage is still on the house, treat the clock as already running and confirm the specifics with the servicer rather than with anybody else.
How selling a house with a reverse mortgage in Plainview works
- 1
You give us the address
The street address in 11803 and a sentence or two about the condition, by phone or the form. No photos needed, and nothing has to be cleaned or repaired first.
- 2
We walk through it once
A single visit by one person, normally under thirty minutes. With a ranch or split-level built when most of Plainview was, the roof, heating and electric matter far more to us than the kitchen does.
- 3
A written offer within 24 hours
One figure, in writing, inside 24 hours. Not a range. Show it to a Nassau County agent if you want a second view; if the house is already in good enough shape to list, an agent may get you more, and we will say so.
- 4
You pick the closing date
Fast if you need fast, or months out if you are waiting on probate, a tenant, or somewhere to move to. Either way you skip the 73 to 88 days a listed Plainview house spends finding a buyer and then waiting on that buyer's mortgage.
The four ways out of a reverse mortgage
Heirs sometimes decide a reverse mortgage has swallowed the house and there is nothing left to save. Sometimes that is correct, and a deed in lieu is a reasonable end to it.
Check first, though. We have seen families walk away from real equity because the reverse mortgage balance looked larger than it was, or because nobody compared it against what the Plainview house would actually sell for. Get the payoff, get a written offer, then decide. Both are free and both take days.
Common questions
The borrower has died. How long do we have to sell the Plainview house?
Ask the reverse mortgage servicer in writing immediately, and do not rely on what anyone tells you verbally. Get an attorney involved early. The window is real but extensions are sometimes granted, and a signed contract is the strongest support for asking.
What if the reverse mortgage balance is more than the house is worth?
It happens, and it is not automatically a disaster for the heirs. Depending on the reverse mortgage, liability can be capped against appraised value. Get the documents read properly before anyone concludes the family owes the difference.
Can we get an extension on the reverse mortgage deadline?
Sometimes, and a pending sale is the best reason to ask. We will sign quickly so your attorney has something concrete to bring to the servicer. Whether they grant it is their decision, not ours and not yours.
Mom moved into a nursing home. Is her reverse mortgage due now?
Quite possibly, because a reverse mortgage generally requires the borrower to occupy the home. A permanent move into care can trigger the payoff. Confirm it with the servicer in writing rather than assuming either way.
Does the servicer have to approve the sale?
They have to be paid off at closing, which is a different thing from approving a buyer. If the sale covers the reverse mortgage payoff, the mechanics are those of an ordinary closing with a firm deadline attached.